October 21, 2026 | By Admin
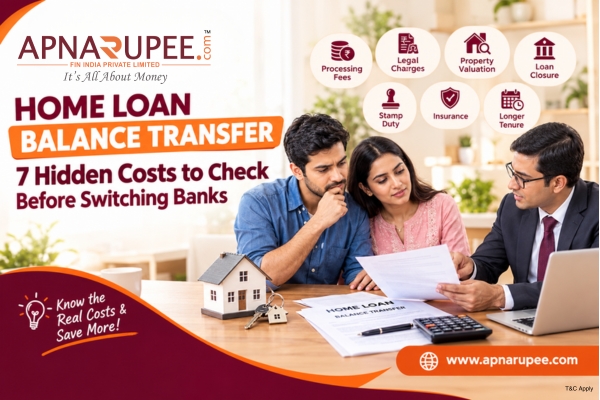
Home Loan Balance Transfer: 7 Hidden Costs You Should Check Before Switching Banks
Thinking of transferring your home loan to another bank for a lower interest rate? A home loan balance transfer can help you reduce your interest burden, manage your EMI, or access better loan terms. However, before making the switch, it is important to look beyond the advertised interest rate.
Some borrowers focus only on the new interest rate and overlook processing fees, documentation expenses, insurance conditions, and other potential costs. These expenses can reduce the financial benefit of switching lenders.
In this guide, ApnaRupee explains 7 potential home loan balance transfer costs you should check before switching banks so you can make a more informed financial decision.
What Is a Home Loan Balance Transfer?
A home loan balance transfer is the process of moving your outstanding home loan from your existing lender to another bank or housing finance company that offers more suitable terms.
For example, suppose your current home loan interest rate is higher than the rate offered by another lender. If you qualify for the new offer, transferring your outstanding loan may help you reduce future interest payments.
However, the actual benefit depends on several factors, including:
-
Your outstanding loan amount
-
The remaining loan tenure
-
The difference between the old and new interest rates
-
The new lender's fees and charges
-
Your eligibility and repayment history
Remember: A lower interest rate does not automatically mean a cheaper loan. Always calculate the overall savings after accounting for applicable transfer costs.
1. Home Loan Processing Fees
One of the first expenses to check is the processing fee charged by the new lender.
Banks and housing finance companies may charge a fee to process your balance transfer application, assess your eligibility, and complete the required formalities.
Depending on the lender, this may be a fixed amount or a percentage of the loan amount.
What should you check?
-
Is the processing fee fixed or percentage-based?
-
Is GST applicable to the fee?
-
Is there a promotional offer or waiver?
-
Is the fee refundable if the loan is not approved or disbursed?
-
Are there any additional administrative charges?
Smart tip: Ask the new lender for a written list of all applicable charges before submitting your application. Do not assume that a low advertised interest rate also means low processing fees.
2. Legal Verification and Documentation Charges
When you transfer a home loan, the new lender may need to verify your property documents and examine the legal status of the property.
This process helps the lender assess whether the property meets its lending requirements.
Depending on the lender and the transaction, you may encounter legal scrutiny fees, documentation charges, or other administrative expenses.
Documents that may need verification
-
Property sale deed or agreement
-
Existing home loan sanction letter
-
Outstanding loan statement
-
Property title documents
-
Previous lender's loan-related documents
-
Other documents requested by the new lender
The exact requirements vary according to the lender, property, and loan structure.
Smart tip: Request a detailed cost estimate covering legal verification and documentation. Confirm whether these charges are included in the processing fee or billed separately.
3. Technical Valuation and Property Inspection Fees
The new lender may arrange a technical inspection or valuation of your property.
This assessment helps determine the property's condition, market value, and suitability as security for the proposed loan.
Depending on the lender's policy, an inspection or valuation fee may apply.
Why does property valuation matter?
A property's valuation can influence the amount the lender is willing to finance. If the assessed value differs significantly from your expectations, the proposed loan terms or eligible amount may change.
Before proceeding, ask:
-
Is a property valuation required?
-
Is there a separate inspection fee?
-
Will the property need to be inspected again?
-
What happens if the valuation is lower than expected?
Smart tip: Check the valuation-related charges in advance, especially if you have already paid for a property valuation during an earlier loan transaction.
4. Charges Related to Closing Your Existing Loan
Before the new lender can take over your home loan, your existing loan generally needs to be settled according to the lenders' transfer procedures.
Ask your current lender for a foreclosure or loan closure statement showing the outstanding amount and any applicable charges.
Are foreclosure charges always applicable?
No. The applicable rules depend on the loan type, borrower, lender, and other relevant conditions.
For example, RBI guidelines generally prohibit regulated lenders from charging foreclosure or prepayment penalties on floating-rate term loans taken by individual borrowers for non-business purposes. Fixed-rate loans and other circumstances may be subject to different rules. Check the terms applicable to your particular loan. See the RBI guidance on foreclosure charges.
You should also ask your current lender about:
-
The exact outstanding principal
-
Interest payable up to the settlement date
-
Any legitimate unpaid dues
-
The validity period of the closure statement
-
The process for releasing the property's original documents
Smart tip: Do not assume that a foreclosure penalty applies—or that every loan closure is completely free. Request a written settlement statement and verify each charge.
5. Stamp Duty, Registration and Mortgage-Related Charges
Depending on the state, the lender, and the method used to create or modify the mortgage, certain stamp duty, registration, or mortgage-related expenses may apply.
These costs are not identical across India. They can vary depending on local rules and the specific documentation required for your transfer.
Questions to ask before switching
-
Is any new mortgage document required?
-
Will stamp duty apply to the new documentation?
-
Are registration or filing charges applicable?
-
Are any charges payable to a local authority or other institution?
-
Who is responsible for paying each expense?
Smart tip: Ask the new lender for a state-specific estimate. Do not rely on a generic online calculator for charges that depend on local rules and your particular transaction.
6. Insurance and Optional Add-On Products
During the balance transfer process, you may be offered home loan protection insurance or other insurance products.
Insurance may provide valuable protection, depending on your circumstances and the policy terms. However, you should understand the premium, coverage, exclusions, and payment arrangements before accepting any product.
What should you verify?
-
Is the insurance optional or required under the specific loan arrangement?
-
What risks does the policy cover?
-
What exclusions and waiting periods apply, if any?
-
Is the premium paid upfront or through another arrangement?
-
Are you being offered a new policy when existing coverage may already meet your needs?
Do not assume that every insurance product offered during a balance transfer is mandatory. Ask the lender to explain the basis for any requirement and provide the relevant terms in writing.
Smart tip: Compare insurance coverage separately from the loan interest rate. Avoid accepting an additional product without understanding its total cost and benefits.
7. The Hidden Cost of Extending Your Loan Tenure
This is one of the most important factors borrowers sometimes overlook.
A new lender may offer a lower EMI by extending the repayment period. While this can improve monthly cash flow, it may also increase the total interest payable over the life of the loan.
Consider a simplified illustration:
Suppose you have a substantial outstanding balance and only 10 years remaining on your current home loan. The new lender offers a lower interest rate but proposes a fresh 20-year repayment period.
Your monthly EMI may fall, but you could end up paying interest over a much longer period.
How can you avoid this mistake?
Compare both loans using the same outstanding principal and a comparable remaining tenure.
Review these three figures:
-
Your current EMI and remaining interest payable.
-
Your proposed EMI and remaining interest payable after transfer.
-
Your total transfer expenses and any other additional costs.
Smart tip: If your budget allows, ask the new lender to calculate the EMI using your existing remaining tenure. This helps you compare the offers more fairly.
How to Calculate Whether a Home Loan Balance Transfer Is Worth It
Before switching lenders, calculate your estimated net savings.
Simple formula:
Net estimated savings = Interest savings over the remaining loan period − Total transfer costs
For a meaningful comparison, use the same outstanding principal and repayment period wherever possible. Account for differences in loan terms and any other costs that affect your actual outgo.
Example: Understanding the impact of transfer costs
Suppose a borrower estimates that switching lenders would save ₹1,50,000 in interest over the remaining repayment period.
The borrower then identifies the following illustrative expenses:
| Expense | Illustrative amount |
|---|---|
| Processing fee | ₹5,000 |
| Legal and documentation costs | ₹4,000 |
| Valuation and inspection | ₹2,000 |
| Other applicable charges | ₹3,000 |
| Total estimated costs | ₹14,000 |
In this simplified example:
Estimated net savings = ₹1,50,000 − ₹14,000 = ₹1,36,000
These amounts are illustrative only, not actual lender quotations. Your result may be different depending on your loan balance, interest rate, tenure, lender fees, and applicable taxes.
Home Loan Balance Transfer Checklist
Before finalising your decision, use this checklist:
-
Obtain your latest outstanding loan statement.
-
Compare interest rates and loan terms from different lenders.
-
Request a written estimate of all transfer charges.
-
Verify applicable foreclosure and prepayment rules.
-
Ask about legal verification and property valuation expenses.
-
Review any proposed insurance or add-on products.
-
Compare the remaining repayment tenure.
-
Calculate total interest savings after all costs.
-
Read the new sanction letter and loan agreement carefully.
Frequently Asked Questions
1. Is a home loan balance transfer always beneficial?
No. It depends on the difference between your current and proposed interest rates, your outstanding balance, the remaining tenure, your eligibility, and the costs involved. Compare the total financial impact before deciding.
2. Can I transfer my home loan to another bank at any time?
You can approach another lender to explore a balance transfer, but approval depends on the new lender's eligibility criteria, property assessment, documentation, and repayment assessment. Your existing loan must also be settled through the required process.
3. Does a home loan balance transfer affect my CIBIL score?
A lender may check your credit report when evaluating your application. The effect on your credit score can vary depending on the circumstances and credit reporting. Maintain timely repayments and avoid submitting unnecessary applications to multiple lenders.
4. Will my EMI definitely decrease after a balance transfer?
Not necessarily. Your EMI depends on the interest rate, outstanding principal, repayment tenure, and loan structure. A lower EMI may result from a longer tenure rather than interest savings alone.
5. Which documents are commonly required for a home loan balance transfer?
Commonly requested documents include identity and address proof, income documents, existing loan statements, repayment records, the original sanction letter, and property documents. Requirements vary by lender and borrower profile.
6. How do I know whether the transfer costs are reasonable?
Ask for an itemised estimate and compare the total cost across lenders. Check the lender's official fee schedule and the applicable terms of your loan.
Final Thoughts
A home loan balance transfer can be a useful way to review your borrowing costs and explore better loan terms. However, the right decision requires more than comparing two interest rates.
Check all seven potential costs—processing fees, legal documentation, property valuation, existing loan closure, mortgage-related expenses, insurance products, and the impact of a longer tenure—before switching lenders.
A careful comparison can help you understand whether the transfer is likely to provide meaningful savings over the remaining loan period.
Explore Your Home Loan Options with ApnaRupee
Considering a home loan balance transfer or looking for suitable home loan options? Explore the available options through ApnaRupee and compare the terms, eligibility requirements, and costs before making a decision.
Visit: https://www.apnarupee.com/
Disclaimer: This article is for general educational purposes only and does not constitute financial, legal, or tax advice. Interest rates, eligibility, fees, and other conditions vary by lender and borrower. Verify all terms with the relevant financial institution before making a decision.