October 27, 2026 | By Admin
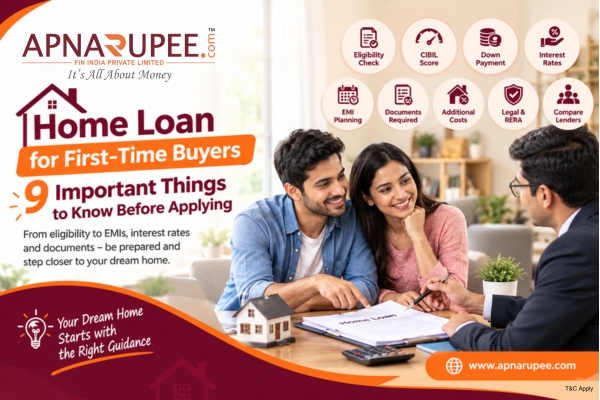
Home Loan for First-Time Buyers: 9 Essential Tips
Buying your first home? Discover 9 essential home loan tips, from eligibility and CIBIL score to interest rates, EMIs, documentation, and hidden charges.
Buying your first home is one of life's biggest financial milestones. Whether you are planning to purchase an apartment in Pune, a house in Mumbai, or your dream home anywhere in India, choosing the right home loan is just as important as choosing the right property.
For first-time homebuyers, understanding home loan eligibility, interest rates, down payments, and repayment options can make the entire process easier and more financially manageable.
At ApnaRupee Fin India Pvt. Ltd., we understand that every homebuyer's financial journey is different. Here are 9 important things you should know before applying for your first home loan in India.
1. Understand Your Home Loan Eligibility Before Applying
Before searching for your dream property, understand how much home loan you may qualify for.
Banks and NBFCs typically evaluate several factors:
-
Your monthly income and employment stability
-
Your age and remaining working years
-
Your CIBIL score and credit history
-
Your existing loans and monthly EMIs
-
Your repayment capacity
-
The property's valuation and legal status
Pro Tip: Check your estimated home loan eligibility before finalising your property budget. This helps you shortlist homes that fit your finances.
2. Maintain a Healthy CIBIL Score
Your CIBIL score plays an important role in determining your home loan eligibility and the interest rate a lender may offer.
A score of 750 or above is generally considered favourable by many lenders, although approval criteria vary.
To improve your credit profile:
-
Pay credit card bills and loan EMIs on time.
-
Avoid applying for multiple loans within a short period.
-
Keep credit card utilisation under control.
-
Check your credit report for errors.
-
Maintain a responsible repayment history.
Remember: A good CIBIL score can strengthen your application, but it does not guarantee home loan approval.
3. Plan Your Down Payment Carefully
Most lenders do not finance 100% of a property's purchase price. You generally need to contribute a portion from your own savings.
For example, consider a property worth ₹50 lakh.
| Particulars | Amount |
|---|---|
| Property value | ₹50,00,000 |
| Illustrative down payment (20%) | ₹10,00,000 |
| Home loan amount | ₹40,00,000 |
This is only an illustration. Actual financing depends on lender policies, applicable loan-to-value limits, property valuation, and other eligibility conditions.
You should also budget separately for stamp duty, registration charges, moving expenses, and other property-related costs.
Pro Tip: Avoid exhausting your emergency savings just to make a larger down payment.
4. Compare Home Loan Interest Rates and Loan Types
Even a small difference in interest rates can significantly affect the total cost of a home loan over 15–25 years.
Home loans commonly offer two interest-rate structures:
Fixed Interest Rate: The rate remains fixed for the agreed period, subject to the loan agreement.
Floating Interest Rate: The rate can change based on the applicable benchmark and lender terms.
Before selecting a lender, compare:
-
Interest rate and annual percentage rate, where disclosed
-
Processing fees
-
Reset frequency for floating rates
-
Prepayment and foreclosure conditions
-
Other applicable charges
Pro Tip: Compare the overall borrowing cost, not just the advertised interest rate.
5. Choose an EMI That Fits Your Monthly Budget
Your Equated Monthly Instalment (EMI) is the amount you repay every month toward your home loan.
Consider this illustrative example:
Home Loan Amount: ₹40,00,000
Assumed Interest Rate: 8.5% per annum
| Loan Tenure | Approx. Monthly EMI |
|---|---|
| 15 years | ₹39,390 |
| 20 years | ₹34,713 |
| 25 years | ₹32,209 |
Figures are approximate, assuming a constant interest rate and standard monthly reducing-balance EMI calculation. Actual EMIs may vary.
A longer loan tenure reduces your monthly EMI but generally increases the total interest paid.
Pro Tip: Choose an EMI that leaves enough money for essential expenses, savings, insurance, and unexpected financial needs.
6. Keep Your Home Loan Documents Ready
Having the necessary documents ready can make your application process smoother.
Common documents include:
For Salaried Applicants:
-
PAN card and acceptable identity/address proof
-
Recent salary slips
-
Bank statements
-
Form 16 or income tax returns, as required
-
Employment details
For Self-Employed Applicants:
-
PAN card and KYC documents
-
Income tax returns
-
Business financial statements
-
Business registration or continuity proof
-
Bank statements
Property-Related Documents:
-
Agreement for sale or sale deed, as applicable
-
Property ownership and title documents
-
Approved building plans
-
Required approvals and permissions
-
Other documents requested by the lender
Document requirements differ by lender, applicant profile, and property type.
7. Don't Ignore Additional Home Buying Expenses
First-time homebuyers often focus on the property price and monthly EMI while overlooking additional costs.
These may include:
-
Stamp duty and registration charges
-
Home loan processing fees
-
Legal and technical verification charges
-
Property insurance, where applicable
-
Maintenance deposits
-
Interior and furnishing expenses
Example: If your property costs ₹60 lakh, your actual initial cash requirement may be significantly higher than the down payment alone.
Pro Tip: Prepare a complete home-buying budget before signing a property agreement.
8. Check the Property's Legal Status and RERA Details
Before applying for a home loan, verify that the property has the necessary legal documentation and approvals.
Important checks include:
-
Ownership and title verification
-
Encumbrances and outstanding dues
-
Approved building plans
-
Required construction and occupancy permissions
-
Applicable RERA registration and project details
For projects in Maharashtra, buyers can verify relevant project information through the official MahaRERA portal.
Remember that a lender's property verification does not replace your own independent legal due diligence.
Pro Tip: Consider consulting a qualified property lawyer before making a major financial commitment.
9. Compare Multiple Lenders Before Making Your Final Decision
Every bank and NBFC has different home loan eligibility criteria, interest rates, documentation requirements, and processing policies.
Comparing multiple lenders can help you identify a suitable financing option based on your income, credit profile, property, and repayment capacity.
Before accepting a loan offer, carefully review the sanction letter, Key Facts Statement where applicable, repayment schedule, fees, and other terms.
How ApnaRupee Can Help
At ApnaRupee Fin India Pvt. Ltd., we aim to simplify your home loan journey by helping you explore suitable financing options through our lending network.
Whether you are a salaried professional, a self-employed individual, or purchasing your first family home, our team can assist you with understanding available home loan options and the application process.
All loan offers, interest rates, eligibility, and approvals remain subject to the respective lender's policies and verification.
Conclusion: Make Your First Home Purchase a Smart Financial Decision
Buying your first home should be an exciting milestone, not an overwhelming financial experience.
By understanding your eligibility, maintaining a healthy credit score, planning your down payment, comparing interest rates, and reviewing property documents, you can make a more informed home loan decision.
The right home loan is not simply the one with the lowest EMI. It is the one that fits your financial goals, repayment capacity, and long-term plans.
Ready to Take the First Step Toward Your Dream Home?
Explore home loan options with ApnaRupee and take the next step toward homeownership with greater confidence.
Visit: www.apnarupee.com
Disclaimer: This article is for general educational purposes only. Interest rates, lending rules, tax benefits, and eligibility criteria may change. Loan approval is at the sole discretion of the respective lender.
Frequently Asked Questions (FAQs)
Q1. What is the minimum CIBIL score required for a home loan?
There is no single minimum CIBIL score applicable to all lenders. A score of 750 or above is often favourable, but some lenders may consider applications with lower scores depending on income, repayment capacity, and other factors.
Q2. Can I get a home loan with a salary of ₹25,000?
It may be possible, depending on your existing EMIs, monthly income, credit history, desired loan amount, tenure, and lender eligibility criteria.
Q3. How much down payment is required for a first home?
The required down payment depends on the property value, applicable loan-to-value limits, lender policies, and valuation. Buyers should also maintain savings for registration, stamp duty, and other expenses.
Q4. Is a fixed or floating home loan interest rate better?
Both have advantages. Fixed rates provide greater repayment predictability for the agreed period, while floating rates may benefit from reductions in benchmark interest rates but can also increase.
Q5. Can a first-time homebuyer apply for a joint home loan?
Yes. Many lenders allow eligible co-applicants, such as spouses or family members, subject to their policies. A joint application may improve eligibility when qualifying incomes are considered together.
Q6. Can I repay my home loan before the end of the tenure?
Many home loans allow partial or full prepayment. Applicable charges and conditions depend on the loan type, borrower category, lender, and prevailing regulations.